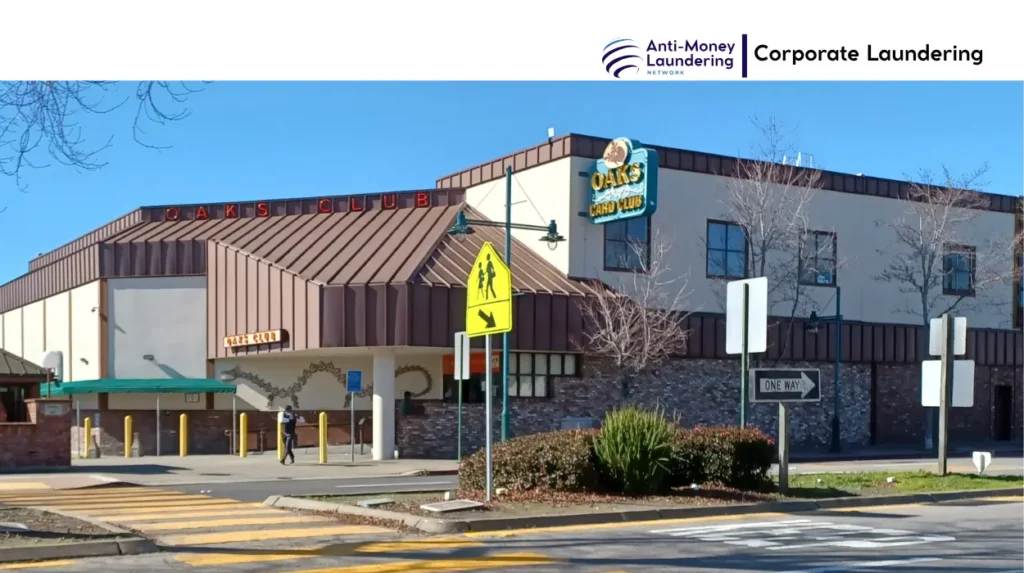
Oaks Card Club is a long-established card-room gaming business in Emeryville, California, United States. While it has operated continuously since the late 19th century, its significance for Anti–Money Laundering (AML) professionals stems from a 2015 enforcement action by the U.S. Financial Crimes Enforcement Network (FinCEN) over Bank Secrecy Act (BSA) violations. The case did not establish that Oaks Card Club itself knowingly laundered criminal proceeds, but it did find willful failures in its AML program, Customer due diligence (CDD), Know Your Customer (KYC) practices, and Suspicious transaction reporting.
The Oaks Card Club FinCEN enforcement action is significant because it was FinCEN’s first civil enforcement action against a card club. It illustrates how a cash-intensive business in the gaming sector can become a vector for Money Laundering risks even without offshore structures or complex corporate layering. For compliance practitioners, the case underscores the importance of robust Corporate Governance, accurate risk assessments, and timely Suspicious transaction reporting in jurisdictions like the Oaks Card Club United States environment.
Background and Context
Oaks Card Club Emeryville traces its origins to the 1890s and is often described as the oldest card club in Northern California. The club’s physical address is 4097 San Pablo Avenue, Emeryville, CA 94608, and it operates as a 24-hour facility, commonly referenced as Oaks Card Club open 24 hours. Its core offering includes a Oaks Card Club poker room with multiple table games, including Oaks Card Club Texas Hold’em, Oaks Card Club Omaha, Oaks Card Club Pai Gow Poker, and Oaks Card Club blackjack, alongside other Oaks Card Club games.
Before the 2011–2015 regulatory and enforcement period, Oaks Card Club California functioned as a conventional, family-associated card club under California gambling-control oversight. Licensing documents from the California Gambling Control Commission in 2025 identify Oaks Club Room, L.P. as the operating entity, with John Cole Tibbetts as general partner and various Tibbetts-related trusts and individuals as limited partners. There is no evidence in the reviewed materials that Oaks Card Club operated as a Oaks Card Club Shell company, Oaks Card Club Offshore entity, or complex holding structure. Its risk profile arises from its sector and control failures, not from opaque corporate engineering.
The timeline leading to exposure of illicit or suspicious activity began with federal and state investigations into loan-sharking and racketeering involving certain employees and patrons. A federal grand jury indictment in February 2011 and a March 2011 raid on the premises preceded a May 2011 settlement with the California Bureau of Gambling Control. These events set the stage for FinCEN’s later determination that Oaks Card Club had willfully violated BSA requirements between 2009 and 2012.
Mechanisms and Laundering Channels
The Oaks Card Club case does not involve classic Oaks Card Club Trade-based laundering, Oaks Card Club Hybrid money laundering, or cross-border Electronic funds transfer (EFT) schemes. Instead, the risk mechanisms center on domestic cash transactions, chip purchases and cash-outs, and failures to detect and report Linked transactions indicative of Oaks Card Club Structuring.
FinCEN’s assessment highlights several concrete examples. On November 16, 2009, a customer attempted to cash out $5,400 in chips but refused to provide identification. After being told identification was required for that amount, the customer divided the transaction into smaller amounts with another customer. Oaks Card Club failed to obtain the required information and did not file a Suspicious Activity Report (SAR). This is a textbook Oaks Card Club Suspicious transaction scenario where CDD and KYC controls broke down.
On August 9, 2010, the same customer completed two $9,900 cash-out transactions approximately one minute apart. The club filed a Currency Transaction Report (CTR) but did not file a SAR despite the clear appearance of Oaks Card Club Structuring to avoid the $10,000 reporting threshold. FinCEN cited this as evidence of inadequate monitoring of Linked transactions.
Internally, Oaks Card Club maintained an AML policy that instructed employees to warn customers when transactions were approaching the $10,000 CTR threshold. FinCEN concluded that this guidance could encourage customers to structure transactions, thereby increasing Money Laundering risk. This policy deficiency directly undermined Oaks Card Club Customer due diligence (CDD) and Oaks Card Club Name screening practices.
Federal prosecutors also alleged that certain employees and patrons used the club to facilitate illegal loans and racketeering activity, including the provision of gambling chips for extortionate loans. While Oaks Card Club and its owners were not charged in those indictments, FinCEN noted the club’s failure to file SARs related to this criminal activity. This illustrates how a Oaks Card Club cash-intensive business can become intertwined with criminal finance even without a formal Oaks Card Club Fraud scheme at the corporate level.
There is no evidence in the reviewed sources of Oaks Card Club Shell company usage, Oaks Card Club Offshore entity involvement, or Oaks Card Club Beneficial owner concealment through offshore vehicles. Likewise, no Oaks Card Club Politically exposed person (PEP) connections were identified. The primary vulnerabilities were domestic, operational, and compliance-related.
Regulatory and Legal Response
The regulatory and legal response to Oaks Card Club unfolded across state and federal levels. On February 24, 2011, a federal grand jury in the Northern District of California indicted 15 individuals, including Oaks Card Club employees and patrons, on charges related to illegal loans and racketeering. This indictment laid the factual groundwork for later AML scrutiny.
In March 2011, state and federal law enforcement executed a raid on the Oaks Card Club location, seizing records and investigating alleged criminal activity on the premises. On May 9, 2011, Oaks Card Club entered into a stipulated settlement with the California Bureau of Gambling Control. The club agreed to a $550,000 fine, with $275,000 stayed for two years, and committed to enhanced training, security, surveillance and staffing measures. This settlement addressed illegal loan-sharking and controlled-substance sales occurring at the club.
On July 5, 2012, a superseding federal indictment was filed, continuing the criminal proceedings against individuals connected with the club. On December 17, 2015, FinCEN announced its first card-club enforcement action, assessing a $650,000 civil money penalty against Oaks Club Room d/b/a Oaks Card Club for willful BSA violations. FinCEN found that from March 31, 2009, through April 3, 2012, the club failed to maintain an effective AML program, provided misleading training on CTR thresholds, and did not file any SARs in 2009 or 2010. The Oaks Card Club 2015 penalty and Oaks Card Club $650,000 fine resolved FinCEN’s claims for the covered conduct.
The case engaged core U.S. AML laws, including the Bank Secrecy Act and its implementing regulations for casinos and card clubs. It also reflected FATF-style expectations around risk-based AML programs, CDD, KYC, and SAR filing, even though the action was domestic. The FinCEN Oaks Card Club settlement serves as a practical example of how U.S. regulators apply BSA requirements to non-bank, gaming-sector entities.
Financial Transparency and Global Accountability
The Oaks Card Club case exposed weaknesses in Financial Transparency at the operational level rather than through complex corporate structures. Key transparency gaps included inaccurate and outdated AML policies that did not reflect actual risk or regulatory expectations, training materials that could incentivize Oaks Card Club Structuring by alerting customers to CTR thresholds, failure to file SARs despite clear indicators of suspicious behavior and known criminal activity on site, and inadequate monitoring of Linked transactions across cash, chips and customer activity.
From a global accountability perspective, the case reinforced the principle that cash-intensive business sectors outside traditional banking, such as gaming, are critical nodes in the international Anti–Money Laundering (AML) framework. While the Oaks Card Club United States operation did not involve cross-border data sharing or multinational regulators, its lessons align with FATF recommendations on extending AML controls to vulnerable sectors and ensuring that supervisors can enforce compliance effectively.
The case did not directly trigger new U.S. reporting standards or cross-border data-sharing reforms, but it contributed to the broader body of enforcement precedents that inform examiner expectations for card clubs and casinos. For international compliance officers, the Oaks Card Club FinCEN enforcement action demonstrates that domestic gaming entities can attract significant regulatory scrutiny when CDD, KYC, and SAR obligations are neglected.
Economic and Reputational Impact
The Oaks Card Club scandal had several economic and reputational consequences. Financial penalties included a $550,000 state settlement (with part stayed) in 2011 and a $650,000 federal civil penalty in 2015. These fines, while not catastrophic for a long-standing operation, represent a material compliance cost and a public marker of regulatory failure.
Operational changes were also required. As part of the 2011 settlement, Oaks Card Club agreed to enhance training, security, surveillance and staffing. These measures likely increased operating costs and altered day-to-day floor procedures. Reputational risk increased as well. The public association with loan-sharking, racketeering and federal indictments, even if directed at individuals rather than the corporate entity, created a negative narrative around Oaks Card Club Emeryville history. Oaks Card Club reviews and media coverage from that period reflect heightened scrutiny of the club’s environment.
Despite these challenges, Oaks Card Club appears to have remained active. Its official Oaks Card Club website continues to advertise 24-hour operations, Oaks Card Club poker games, and other Oaks Card Club casino offerings. The Oaks Card Club phone number and Oaks Card Club hours remain publicly listed, and the Oaks Card Club parking and physical Oaks Card Club address are unchanged. This suggests that the club managed to preserve its core business while addressing regulatory expectations.
For investors, partners and local stakeholders, the case underscored the importance of monitoring compliance risk in gaming venues. While there is no public stock performance data for Oaks Card Club as a privately held partnership, the episode likely affected lender, insurer and regulator perceptions of the entity’s risk profile.
Governance and Compliance Lessons
The Oaks Card Club case reveals several critical gaps in Corporate Governance and internal controls. FinCEN found that the club’s AML policy was inaccurate and misleading. This indicates a failure of senior management and compliance officers to keep policies aligned with regulatory requirements and operational reality. Training materials that warned customers about CTR thresholds created an incentive for Oaks Card Club Structuring. Effective AML training should emphasize detection and reporting, not threshold-avoidance behavior.
The club filed no SARs in 2009 or 2010, despite suspicious transactions and criminal activity. This reflects a breakdown in the internal escalation and decision-making process for Suspicious transaction reporting. Instances where customers refused to provide identification and transactions were split to avoid thresholds show inadequate Oaks Card Club Customer due diligence (CDD) and Oaks Card Club Know Your Customer (KYC) enforcement at the counter and cage. The failure to connect rapid, near-threshold cash-outs as Linked transactions indicates insufficient transaction-monitoring logic and human oversight.
After the enforcement actions, Oaks Card Club implemented enhanced training, security, surveillance and staffing measures as part of the 2011 settlement. While the FinCEN assessment does not detail all post-2015 reforms, the public continuation of operations suggests that the club brought its AML program into closer alignment with BSA expectations. For other gaming operators, the case serves as a reminder to regularly update AML policies and test them against real-world scenarios, ensure training emphasizes detection and reporting rather than threshold management, maintain robust Name screening, CDD, and KYC procedures at all cash-handling points, and implement transaction-monitoring systems capable of identifying Oaks Card Club Structuring and Linked transactions.
Legacy and Industry Implications
The Oaks Card Club case has left a clear legacy in U.S. AML enforcement. FinCEN explicitly described this as its first enforcement action against a card club. This elevated the profile of non-casino gaming venues in the BSA enforcement landscape. The Oaks Card Club 2015 penalty signaled to other card clubs that they are subject to the same BSA expectations as casinos, including effective AML programs and SAR filing.
Examiners and compliance officers now reference the case when assessing whether gaming entities have adequate controls against Structuring, suspicious cash activity and criminal-use facilitation. The case illustrates how AML enforcement can run in parallel with criminal investigations into loan-sharking and racketeering, reinforcing the need for coordination between compliance, security and legal functions.
While the case did not produce sweeping statutory reforms, it contributed to the normalization of rigorous BSA supervision for card clubs. For the global Anti–Money Laundering (AML) community, it is a practical example of how domestic, non-offshore entities can still pose significant Money Laundering risks when governance and controls are weak.
Oaks Card Club is not a paradigmatic example of elaborate Oaks Card Club Shell company networks, Oaks Card Club Offshore entity structures, or Oaks Card Club Trade-based laundering. Its importance lies in demonstrating how a traditional, cash-intensive business in the U.S. gaming sector can become a focal point for Money Laundering risk through inadequate AML controls, poor CDD and KYC practices, and failure to report Suspicious transaction activity.
The Oaks Card Club FinCEN enforcement action, culminating in the Oaks Card Club $650,000 fine for Bank Secrecy Act violations, underscores the necessity of accurate, up-to-date AML policies and training, strong Corporate Governance and oversight of compliance functions, effective detection of Oaks Card Club Structuring and Linked transactions, and timely SAR filing when criminal activity or suspicious behavior is identified.
For regulators, examiners and compliance professionals, the Oaks Card Club United States case reinforces the continued importance of Financial Transparency, accountability, and robust Anti–Money Laundering (AML) frameworks. It remains a relevant reference point for anyone assessing Oaks Card Club Money laundering risk, Oaks Card Club Fraud exposure, or the broader challenge of safeguarding the integrity of global finance through disciplined, sector-specific compliance.